Old Car Insurance in Malaysia: What You Should Know
 Nabil Farhan· · 2 min read
Table of contents
When your car crosses that 10-year mark, the big question shows up – is Old Car Insurance Malaysia still worth paying full comprehensive, or is third party enough? Insuring an older vehicle isn’t quite the same as a new one. Market value is lower, risks are different, and insurers sometimes apply stricter rules. Let’s walk through what owners of aging cars should really know before renewing.
Why Insurance for Old Cars Is Different
- Older cars = lower market value. If it’s stolen or total loss, payout is usually small.
- That’s why many drivers feel full coverage is overkill.
- But risk is risk: accidents, theft, or fire don’t disappear just because the car is old.
Policy Options for Old Cars
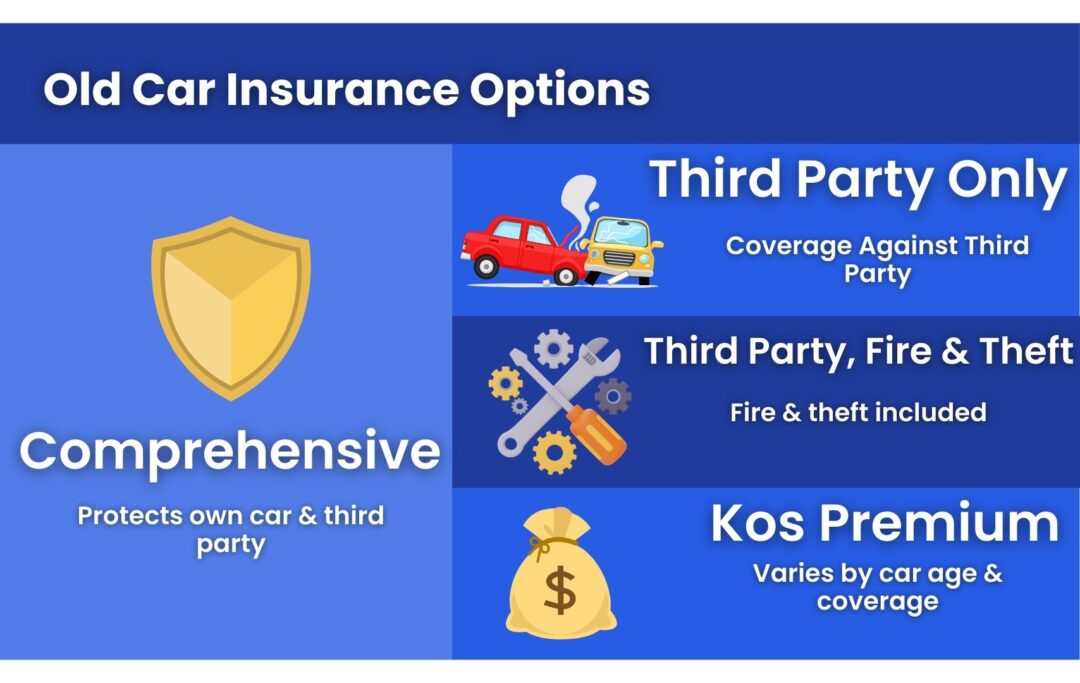
1. Comprehensive
- Protects your own car + third party.
- Best if the car still has solid resale value or you drive long distance often.
2. Third Party Only
- Covers only third-party damage/injury.
- Cheapest option, but repairs for your own car = out of pocket.
3. Third Party, Fire & Theft
- Covers fire & theft, plus third-party.
- Middle-ground choice for older cars prone to theft/fire.
Quick Comparison Table
| Policy Type | What’s Covered | Best For | Premium Cost |
|---|---|---|---|
| Comprehensive | Own car + third party | Old cars with higher value, frequent use | Highest |
| Third Party Only | Third party only | Very old cars, low resale value | Cheapest |
| Third Party, Fire & Theft | Third party + fire & theft | Old cars with theft/fire risk | Moderate |
What Affects Premiums for Old Cars?
| Factor | Effect on Premium |
|---|---|
| Car Age | Older = cheaper comprehensive (low market value) |
| Policy Type | Third party cheapest, comprehensive most costly |
| NCD | No-claim years can save hundreds |
| Risk Factors | Garage parking vs roadside parking matters |
Tips Before Choosing Old Car Insurance
Check market value first – if below RM10k, maybe skip comprehensive.
Read claim conditions – some insurers tighten rules for cars 10+ years.
Think theft risk – models like Wira or Kancil still get stolen often.
Compare prices online – use JPJ/MyJPJ, Pos Malaysia, or Bjak before buying.
Conclusion
At the end of the day, Old Car Insurance Malaysia isn’t about picking the lowest price blindly. It’s about matching policy to your car’s market value, how much you drive, and which risks keep you awake at night. Always compare across platforms, check your NCD savings, and read the small print before locking in your renewal.
Benefits of Online Car Insurance for Long Trips
Frequently asked questions
Can a car over 15 years old still get comprehensive insurance?
Yes, but not every insurer offers it. Some require inspection.
Is third-party insurance enough to renew road tax?
Yes. As long as your insurance is active, JPJ allows road tax renewal.
What’s the cost gap between comprehensive and third party?
It can be hundreds of ringgit. Third party is cheapest, comprehensive costs more but covers both car + liability.