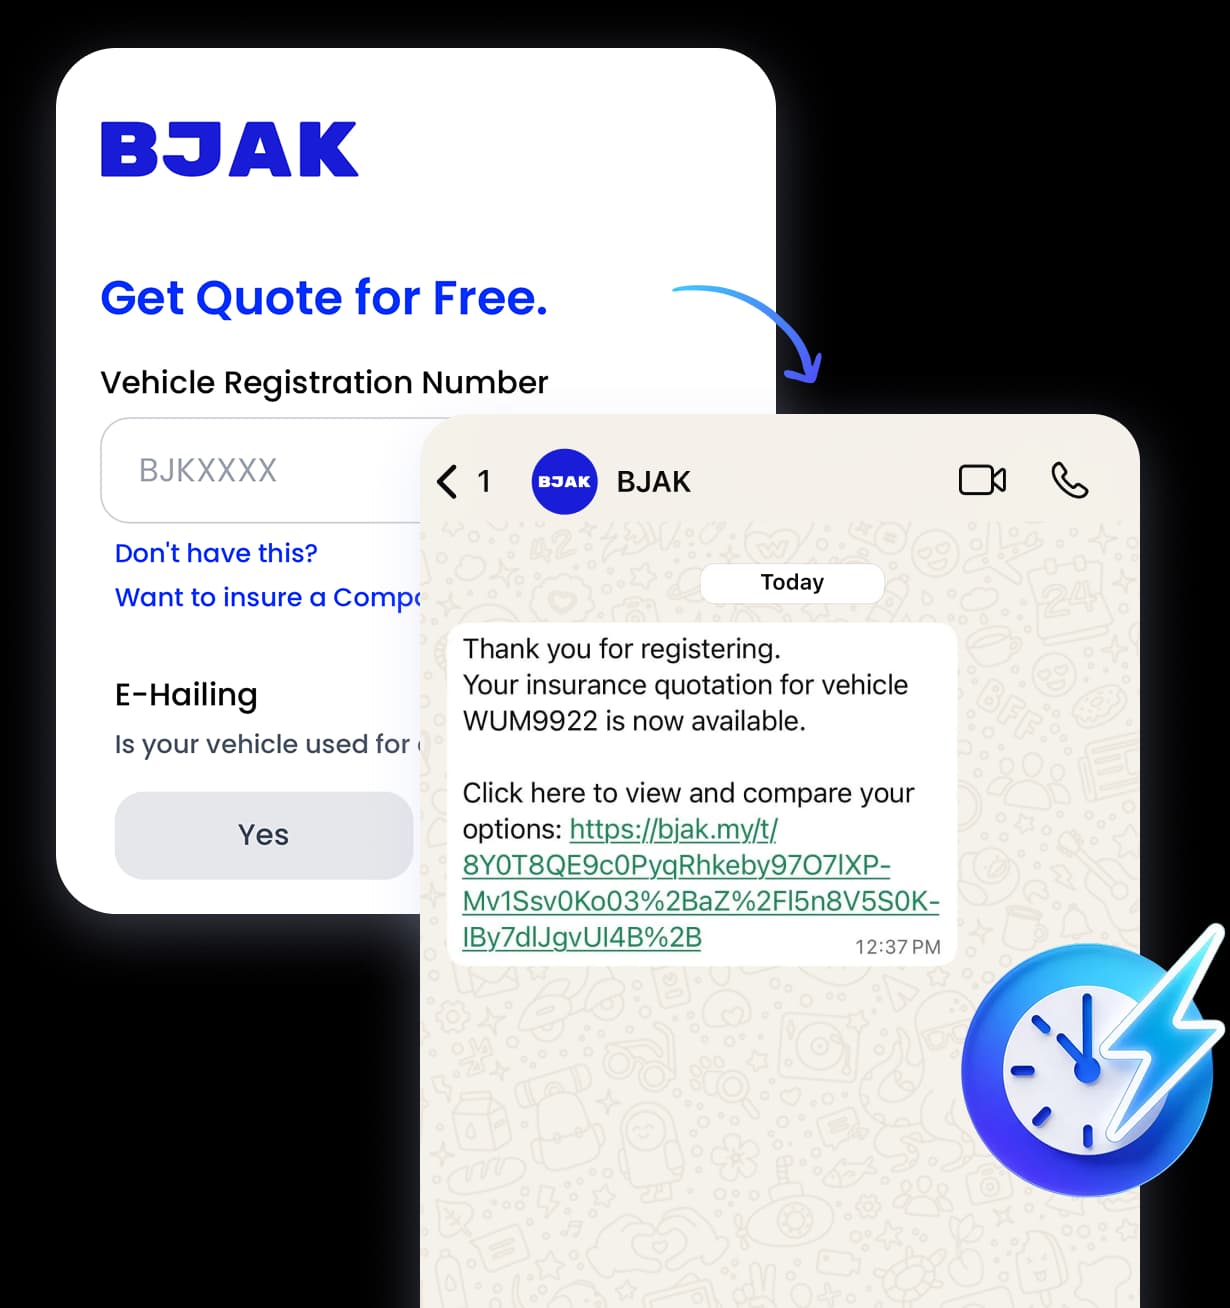






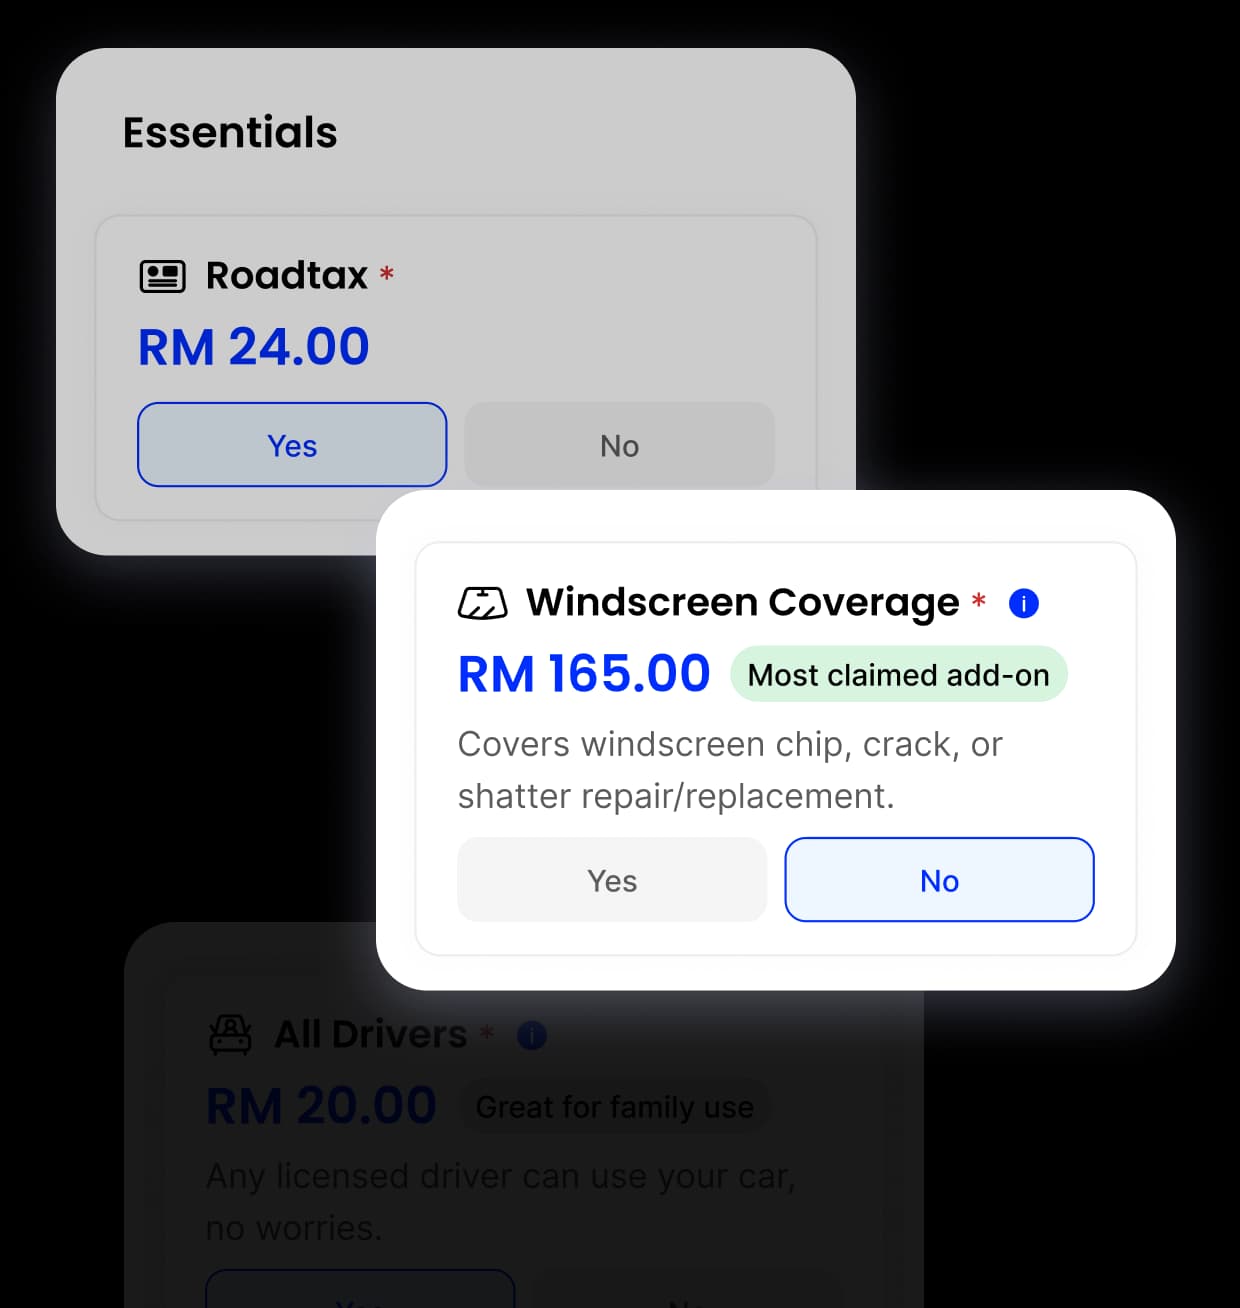
Customise your coverage in seconds
Choose the add-ons you need and see the price instantly.
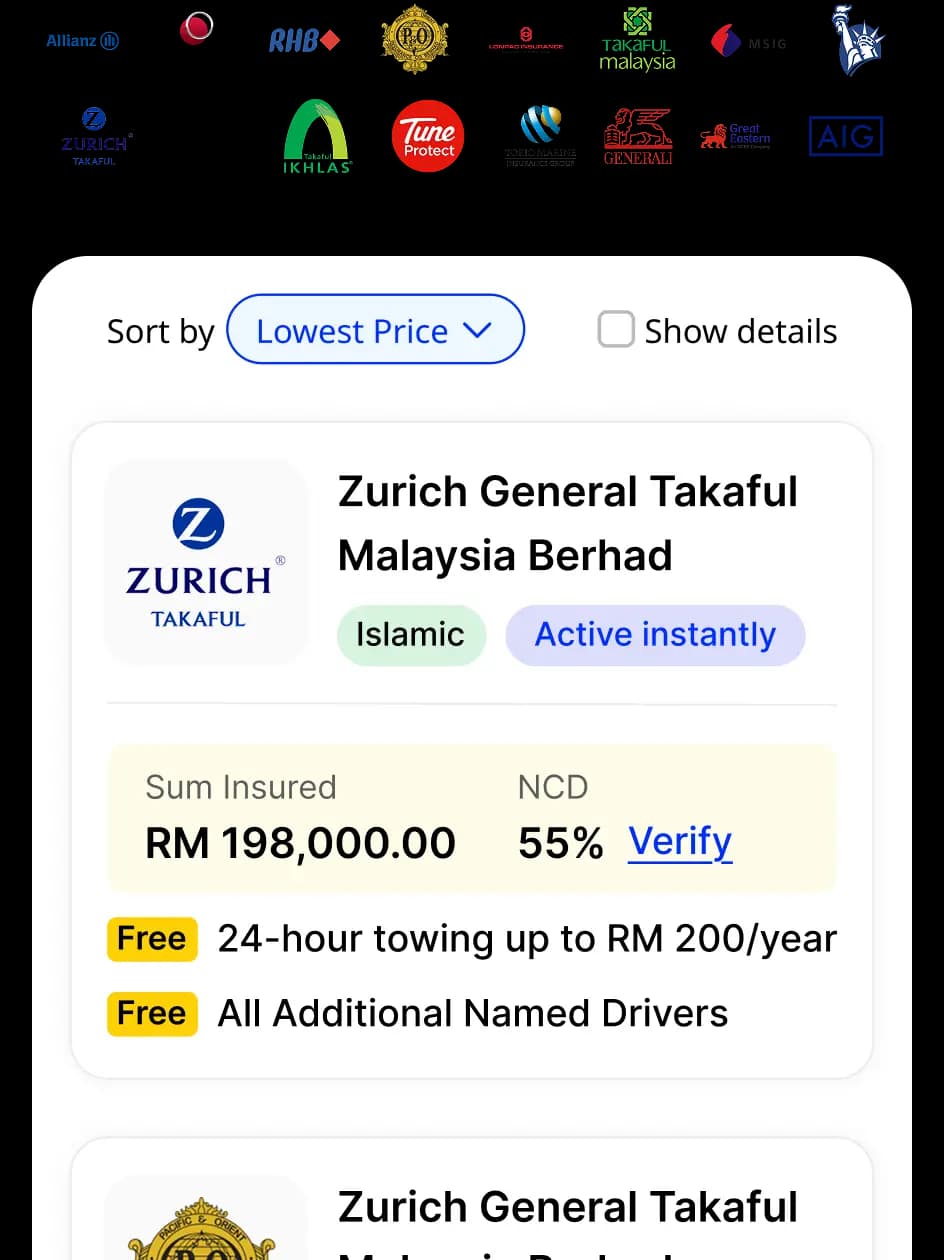
Get quotes from 16 insurers and takaful operators with just your plate number.
 Top 10 Insurtech Company Globally (2026)
BJAK is an approved Financial Adviser and Islamic Financial Adviser under Bank Negara Malaysia (BNM).
Approved Financial Adviser
Approved by Bank Negara Malaysia (BNM)BJAK Sdn. Bhd. (1339813-K / 201901030483)Verify on bnm.gov.my9M+ customers served
People who bought a policy through BJAK since 2019BJAK policy records, as of 17 Oct 2026Find car insurance for private cars, used cars, EVs, e-hailing, business use, low-mileage drivers and foreign drivers in Malaysia.
Compare car insurance quotes from 16 insurers and takaful operators in Malaysia. Check premium, coverage, add-ons, excess and roadside benefits before choosing. View all Car Insurance providers
Comparing pays off. In 85% of quote requests on BJAK, a cheaper option was available, with the lowest quote averaging RM115 (14.8%) below the median. Honda City drivers saw the biggest gap, at RM159.1
| Insurer | Type | Flood | Windscreen | EV | E-hailing | PDS |
|---|---|---|---|---|---|---|
| AIGAIG stands out with Vehicle Break-In, Tyre & Rims and Inconvenience Allowance add-ons, alongside Special Perils and EV insurance options. | Insurance | + | + | + | – | View |
| AllianzAllianz offers e-hailing, Waiver of Betterment and NCD Relief options, giving drivers more flexibility for different types of vehicle use. | Insurance | + | + | + | + | View |
| Berjaya Sompo InsuranceBerjaya Sompo offers a combination of All Driver, All Rider and CART options, giving customers flexibility over who can drive and additional transport protection. | Insurance | + | + | + | – | View |
| ChubbChubb offers customisable motor insurance with 24-hour accident and roadside assistance, supported by its MY Chubb Motor Assist service. | Insurance | + | + | – | – | View |
| Generali MalaysiaGenerali offers Passenger Risk and Hospital Income options, together with NCD Relief and other additional protection. | Insurance | + | + | + | – | View |
| Great EasternGreat Eastern offers Hospital Income and Flood add-ons, alongside its wider range of protection options for private cars. | Insurance | + | + | + | – | View |
| Liberty InsuranceLiberty offers e-hailing and CART add-ons, giving drivers additional options for passenger use and transport-related costs. | Insurance | + | + | – | + | View |
| Lonpac InsuranceLonpac offers CART and All Rider options, providing additional protection for transport costs and riders depending on the selected cover. | Insurance | + | + | – | – | View |
| MSIGMSIG offers NCD Relief, Waiver of Betterment and Strike & Riot as additional protection options for eligible policies. | Insurance | + | + | + | – | View |
| Pacific & OrientP&O stands out with its mileage-based insurance options, with different mileage tiers available for drivers who don't drive as often. | Insurance | + | + | – | – | View |
| RHBRHB offers Spray Paint, Waiver of Betterment and mileage-based options, making it a notable choice for drivers looking for more specialised cover. | Insurance | + | + | + | – | View |
| Takaful IkhlasTakaful IKHLAS offers named-driver options, allowing customers to add multiple drivers to their motor takaful coverage. | Takaful | + | + | – | – | View |
| Takaful MalaysiaTakaful Malaysia stands out with Flood Towing & Cleaning and CART, alongside All Driver and All Rider options. | Takaful | + | + | + | – | View |
| Tokio MarineTokio Marine offers Flood Inconvenience cover, providing an additional benefit for customers affected by flood-related vehicle damage. | Insurance | + | + | – | – | View |
| Tune ProtectTune Protect offers less common options such as Spray Paint and Tune Motor Shield, alongside NCD Relief and Strike & Riot. | Insurance | + | + | – | – | View |
| Zurich TakafulZurich offers Waiver of Betterment and NCD Relief, along with options such as Strike & Riot and Special Perils. | Takaful | + | + | + | – | View |
Listed alphabetically, not ranked. Add-ons are for comprehensive cover. EV and e-hailing cover are from BJAK's insurer product list; the other add-ons are as listed in each insurer's configuration on 19 Oct 2026. Whether one is free for you is decided when you get a quote.
Renewing your car insurance does not mean you have to stay with the same insurer. Before renewing, check your NCD, sum insured, coverage, add-ons and final premium so you know exactly what you are paying for.
With BJAK, you can compare renewal quotes from participating insurers and takaful operators, review the available coverage and add-ons, then renew your car insurance online.
Enter your car details: Enter your vehicle registration number and NRIC to retrieve your renewal information.
Check your NCD: Make sure the NCD shown on your quote matches your current entitlement. You can also use the NCD Checker before renewing.
Compare your renewal quotes: Compare premiums, coverage, sum insured, add-ons and other benefits across available insurers and takaful operators.
Review your policy: Check that your vehicle details, coverage type, sum insured and selected add-ons are correct.
Pay and renew: Choose your preferred payment option and complete your renewal. You can also add road tax to the same transaction where available.
Need to renew your car insurance and road tax? You can renew both online with BJAK in one flow.
Your car insurance needs to be active before your road tax can be renewed. Once your insurance renewal is processed, your road tax renewal can be submitted for JPJ processing. After it is completed, you can check your digital road tax through the MyJPJ app. Our guide explains how to renew car insurance and road tax together step by step.
With BJAK, you can:
Renewing your road tax online can be done after your car insurance is active.
With BJAK, the process starts with your car insurance renewal. Once your insurance is active and the required vehicle details are valid, your road tax renewal can be submitted for JPJ processing.
Renew your car insurance: Make sure your car insurance is active before renewing your road tax.
Add road tax renewal: Choose road tax renewal during the renewal process if you want to renew both together.
Complete payment: Pay online for your selected insurance and road tax renewal.
Road tax is submitted for processing: Once your insurance is active, the road tax renewal is submitted for JPJ processing.
Check your digital road tax: Once processing is complete, you can view your digital road tax in the MyJPJ app.
Pay for your car insurance and road tax using cards, FPX, bank instalment plans or selected Buy Now, Pay Later services such as SPayLater, Grab PayLater and Atome. Options, fees and eligibility vary by provider.
Your policy provides full coverage for the policy period, even when you pay in instalments, subject to successful payments and applicable terms. Learn more about available payment options.
Stay protected today and manage payments at your own pace
3months
RM167/month
(based on RM500 policy)6months
RM84/month
(based on RM500 policy)12months
RM42/month
(based on RM500 policy)
Buy Now, Pay Later options are available at checkout. No pre-selection required.
A standard private-car policy may not cover e-hailing. If you drive for Grab, inDrive or Maxim, you may need an e-hailing endorsement or separate cover. Learn more about e-hailing insurance.
EVs generally use comprehensive insurance, but check whether your policy covers the battery, charger, charging cable and related risks. Get EV car insurance quotes.
Young or less-experienced drivers may have a compulsory excess. Check your policy for age, licence and driver restrictions.
Some insurers offer usage-based cover or discounts if you drive fewer than 10,000 km a year. Check eligibility and mileage limits.
Each vehicle usually needs its own policy. A second car typically starts with 0% NCD, unless you qualify to transfer an existing NCD.
Tell your insurer if you use your car for business. Using a private-car policy for undeclared commercial purposes may affect your coverage or claim.
The No Claim Discount (NCD) reduces your private-car premium for each claim-free year. It is linked to the policyholder and vehicle, and may be transferred to another vehicle under the insurer's rules. PIAM explain the NCD schedule for private cars accumulates as follows:
For example, on a RM1,500 premium, a 55% NCD is worth RM825. If a claim resets your NCD, you may pay more in future premiums while rebuilding the discount. For a RM600 dent, compare the repair cost with the potential loss of your NCD before claiming.
Some claims may not affect your NCD, depending on the policy terms:
Check your registration number using the BJAK NCD checker. NCD transfer is subject to the insurer's rules and generally cannot be split between two vehicles or transferred to another owner. See PIAM's guide to the NCD transfer procedure.
Your renewal quote is not just about the price. Before you renew, check these five things:
Make sure the NCD shown on your renewal quote matches your current entitlement. Your NCD can make a significant difference to your premium, so check it before comparing quotes.
Your car's value may have changed since your last policy. Check whether the sum insured still reflects the value of your car and whether the policy uses market value or agreed value. See our guide to sum insured and market value vs agreed value.
Think about whether your current coverage still suits your car and how you use it. You may need comprehensive, third-party fire and theft, or third-party cover depending on your circumstances.
Check the add-ons you had last year. You may want to keep, remove or add coverage such as:
Available add-ons vary by insurer and policy.
Do not compare the headline premium alone. Check what is included in each quote, including the sum insured, add-ons, excess and other benefits.
You don't have to stay with the same insurer when renewing your car insurance. Your NCD entitlement moves with you, so switching insurers at renewal does not mean losing your NCD.
Instead of comparing price alone, look at the whole package: the premium for similar coverage, sum insured, available add-ons and their prices, as well as the workshop and claims arrangements offered by each insurer.
Yes. Section 90 of the Road Transport Act 1987 makes it an offence to use a vehicle on a public road without insurance that covers death or injury to other people. Third-party insurance is the minimum required cover.
Yes. Your car must have an active insurance policy before JPJ can issue or renew its road tax. You can get a car insurance quote and add road tax to the same payment.
Usually, yes. Most hire-purchase agreements require comprehensive insurance while you are still paying for the car.
You may face a fine, imprisonment or disqualification from driving. You may also have to pay personally for injury or damage caused to other people because you do not have an insurer to cover these costs.
There are three main types of car insurance in Malaysia: comprehensive, third-party fire and theft (TPFT), and third-party cover. Motor takaful offers similar protection under Shariah-compliant principles. PIAM publishes the industry reference.
| What is covered? | Comprehensive | Third-party fire & theft | Third party |
|---|---|---|---|
| Death and injury caused to other people | |||
| Property damage caused to other people | |||
| Fire and theft involving your car | |||
| Accidental damage to your car |
Coverage limits, exclusions and extra benefits depend on the insurer and policy. Check the Product Disclosure Sheet before buying.
Motor Takaful is an alternative to conventional car insurance that follows Shariah principles. It offers the same three main levels of protection:
The cover, exclusions, excess and No Claim Discount can vary by provider, so compare the policy details before choosing. See the Malaysian Takaful Association to learn more about Motor Takaful.
Third-party insurance is usually the cheapest, but you get less protection than with fire and theft or comprehensive cover. For a car worth RM15,000, comprehensive cover could cost just RM200 to RM400 more a year. Compare the prices before you decide, the extra protection might cost less than you think.
Comprehensive insurance covers more risks than other policy types, but it does not cover everything. These are some common exclusions:
The examples below are based on a selected case, a RM50,000 sum insured. Product Disclosure Sheets (PDS) from Zurich, Allianz, Tokio Marine and Takaful Malaysia. Prices, benefits and availability vary by insurer, vehicle and policy. Your quote may differ.
Special perils cover may be worth considering, especially if you live in a flood-prone area. For example, the Zurich Z-Driver PDS gives an example price of RM100 a year for a RM50,000 sum insured. Your price will depend on the insurer, vehicle and policy.
What BJAK customers add most: All Drivers Coverage is in 60.2% of policies, followed by Windscreen Cover (26.2%) and Special Perils Cover for flood, storm and landslide (12.1%). Windscreen Cover averages RM199.82 and Special Perils RM79.60 per policy.2
Car insurance premiums vary by vehicle, driver and coverage. Since motor insurance pricing was liberalised on 1 July 2016, insurers can assess risk and set different premiums, so the same car may receive different quotes.
See BNM's Liberalisation of Motor Insurance and the Phased Liberalisation policy document.
What BJAK customers are quoted: across the 10 most-quoted models, average quotes range from RM338 for the Proton Wira to RM995 for the Honda City. A Perodua Myvi averages RM693, a Proton Saga RM585 and a Toyota Vios RM924.4
Your premium depends partly on your car's insured value, which is generally based on its market value. See sum insured and market value vs agreed value.
Optional add-ons increase the premium, followed by 8% service tax and RM10 stamp duty.
Your age, claims history, vehicle age, location and vehicle usage can affect the premium.
Larger engines generally cost more to insure.
You can receive up to 55% off, making this one of the biggest factors you can control.
Your road tax price depends on factors such as:
For example, road tax rates for private cars in West Malaysia are based on engine capacity, with different rates for saloon and non-saloon vehicles.
You can use the BJAK Road Tax Calculator to check your estimated road tax cost before renewing.
Road tax is now digital for eligible private vehicles, so you do not need to display a physical road tax sticker on your windscreen.
After your road tax renewal is processed, you can view your digital road tax in the MyJPJ app.
If someone else drives your car, MyJPJ also allows you to share the digital road tax with them.
Some car insurance cases need manual checks, including ownership transfers, new cars without a plate number, total-loss vehicles, NCD transfers and vehicle-class changes.
Send us your registration number and one line about your situation. WhatsApp +6016-699 9129, call 03-9213 1717. Contact us
Check for injuries and call 999 if urgent medical help is needed.
Take photos of both vehicles, number plates and the accident scene, if safe.
Exchange details such as contact, licence and insurance information. Avoid admitting fault.
Report the accident to your insurer before agreeing to any roadside settlement.
Use your insurer's approved towing service and avoid unsolicited tow-truck operators.
Make a police report promptly and follow your policy's reporting requirements.
Notify your insurer as soon as possible. BJAK can help coordinate claims for policies issued through BJAK.
Use a panel workshop approved by your insurer.
Check your excess and betterment charges, which may apply depending on your policy and vehicle.
Do not start a flooded car. Starting the engine can cause further damage. Have the vehicle inspected and towed safely.
Simple guides to help you compare coverage, choose add-ons, renew roadtax, and understand claims in Malaysia.
Visit the Learning HubCar insurance protects you financially against specified losses involving your vehicle and third parties. What is covered depends on whether you choose comprehensive, TPFT or third-party cover.
Yes. At least third-party insurance is required to use a vehicle on public roads in Malaysia, and valid insurance is needed before road tax can be renewed.
In Malaysia, 'first-party' commonly refers to comprehensive car insurance. It can cover accidental damage to your own car as well as third-party injury and property-damage liabilities, subject to the policy terms.
Motor takaful is Shariah-compliant vehicle protection based on participant contributions to a shared fund. Coverage, claims, excess and benefits depend on the takaful certificate and operator.
Motor takaful provides similar types of protection to motor insurance, but the underlying contract and fund structure differ. Contributions, claims, excesses and NCD treatment depend on the certificate and the operator's terms. Compare takaful options on our Insurance & Takaful Partners page.
Motor insurance pricing has been progressively liberalised in Malaysia, so insurers can assess risk and price eligible cover differently. That is why the same car can receive different quotes from different insurers.
There is no single fixed price. Your premium depends on factors such as your car's insured value, NCD, driver and vehicle risk, location, usage, insurer and add-ons. Use our Insurance Calculator for an estimate.
Compare quotes from 16 Insurance & Takaful Partners side by side. Check the premium, coverage, excess, add-ons and benefits before choosing the lowest-priced suitable policy.
Your eligible NCD can usually be carried over when you switch insurers, subject to insurer rules. Check your current entitlement with our NCD Checker.
The compulsory excess on an own-damage claim when the driver is under 21, holds a P or L licence, or is not named on the policy schedule. All-drivers cover removes the unnamed-driver trigger, but not the age or licence ones.
Yes. Comparing car insurance quotes on BJAK is free. BJAK may receive a commission from the insurer you choose; check the Product Disclosure Sheet and final payment details before buying.
Standard comprehensive car insurance usually does not include flood damage automatically. You may need a Special Perils add-on, subject to the insurer's terms and availability.
A glass-only claim under an eligible windscreen add-on usually does not reduce your NCD. Without that add-on, the claim may be treated differently under your policy. Check your NCD and policy terms.
If you use your car for e-hailing, you generally need cover that specifically allows e-hailing or hire-and-reward use. A normal private-car policy may not cover claims made while carrying paying passengers.
It provides nationwide towing with no mileage caps for members. For a full list of roadside privileges, check the VIP Benefits page.
Yes. You can compare and renew your car insurance first, then add road tax to the same transaction where available. Use our Roadtax Calculator to check the road tax amount.
Many insurers allow renewal before your current policy expires, commonly up to about two months in advance. Your new policy start date should follow the current policy's expiry date.
Digital records update on the MyJPJ App within 30 minutes. To check specific fees, use our Roadtax Calculator.
Yes, eligible payment options can include monthly instalments, BNPL and credit-card plans. Available terms depend on the provider. See our Payment Options.
You should not drive without valid insurance. You also cannot renew road tax without active insurance, and you may have to pay claims personally if you cause injury or damage while uninsured.
Contact the BJAK 24/7 VIP Hotline for immediate towing and claims coordination.
Ask the insurer for the reason in writing and use its complaints process first. If the dispute is eligible and remains unresolved, you can escalate it to the Financial Markets Ombudsman Service.
No. Your car insurance needs to be active before your road tax can be renewed. If your insurance has expired, renew it first before proceeding with your road tax renewal.
Road tax prices depend on factors such as your engine capacity, vehicle type, region and ownership type. You can use a road tax calculator to check the estimated price for your vehicle.
Yes. You can renew your road tax online with BJAK. Your insurance must be active before the road tax renewal can be processed.
You can check your digital road tax through the MyJPJ app. Go to Profile → Vehicle, select your vehicle and open the digital road tax.
For eligible private vehicles, road tax is digital and can be viewed through MyJPJ. A physical sticker is not required.
No. You need to renew your car insurance and make sure it is active before your road tax can be renewed.
Road tax renewal may be affected by outstanding summonses or blacklist records. Outstanding offences may need to be settled before renewal can proceed.
This depends on the vehicle's registration and applicable requirements. Company-owned or commercial vehicles may have different road tax renewal requirements.
Yes, as long as the vehicle meets the requirements for renewal and has active insurance. If you have recently bought a used car, make sure the ownership and vehicle details are updated correctly before renewing.
Reviewed 16 Oct 2026 by Ronald Lim
Insurance and Takaful Expert
Ronald Lim is the Group CEO of BJAK and reviews our car insurance content to help ensure accuracy and reliability. He holds multiple insurance and takaful qualifications, along with Registered Financial Planner (RFP) and Shariah Registered Financial Planner (Shariah RFP) designations from the Malaysian Financial Planning Council.
Our car insurance guides are reviewed against insurers' policy documents, product disclosures and relevant industry sources to help Malaysians make informed decisions when comparing coverage and premiums.
Based on BJAK internal quote data covering 5,154,622 quote requests. Potential savings are the median premium minus the lowest premium for each request. Premiums are grouped into RM50 bands, and requests with RM0 premiums are excluded. These are not guaranteed savings for every customer. Source: Average Savings on Car Insurance After Comparing Insurers
Based on BJAK customer policy data. Pickup rate is the share of policies in the dataset that include each add-on. Average price is the average gross written premium attributed to each add-on, not a guaranteed price. Availability and premiums vary by insurer and policy. Source: Most Selected Car Insurance Add-Ons Among BJAK Customers
Based on BJAK internal quote data: 5,143,368 petrol (ICE) quotes across 4,609 models and 11,257 EV quotes across 146 models. Plug-in hybrids are grouped under ICE. Average is total premiums divided by number of quotes. Figures reflect BJAK quote data, not the whole Malaysian market. Source: EV vs Petrol Car Insurance in Malaysia
Based on the BJAK Make-Model Average Gross Premium dashboard, snapshot of 1 October 2026, for the 10 models with the highest quote volumes on BJAK. Averages are estimated using RM50 price bands, and RM0 quotes are excluded. These are not guaranteed prices or current quotes. Source: Average Car Insurance Price in Malaysia by Car Model on BJAK