
All Drivers Coverage: Do You Need It?
 Nabil Farhan· · 4 min read
Table of contents
Generally, car insurance covers the policyholder and drivers who meet the terms of the policy. But what happens if you let your friend, spouse, child, or another family member drive your car?
Here is what you need to know about All Drivers Coverage before you hand your keys to someone else.
Can anyone drive your car?
Yes, you can allow someone else to drive your car, provided they meet the strict requirements of your insurance policy. The driver must:
- Have a valid driving licence for the type of vehicle.
- Have your explicit permission to drive the car.
- Follow the terms and conditions of your car insurance policy.
However, giving someone permission to drive does not automatically protect you from paying a compulsory excess if they make a claim. This is where Named Driver and All Drivers Coverage become important.
What happens if you don’t name your driver?
If someone who is not named in your policy drives your car and gets into an accident, a compulsory excess of RM400 may apply to an own-damage claim. This RM400 fee is triggered when the driver:
- Is not named in the policy schedule.
- Is below 21 years old.
- Holds a probationary (P) or learner (L) driving licence.
For example, if a friend borrows your car with your permission and causes an accident, you may have to bear the first RM400 of the repair costs, while the remaining amount is handled according to your policy terms.
Important: All Drivers Coverage can waive the RM400 excess for an unnamed driver, but it does not automatically remove the RM400 excess that applies if the driver is under 21 or holds a P/L licence.
Named Driver vs. All Drivers Coverage
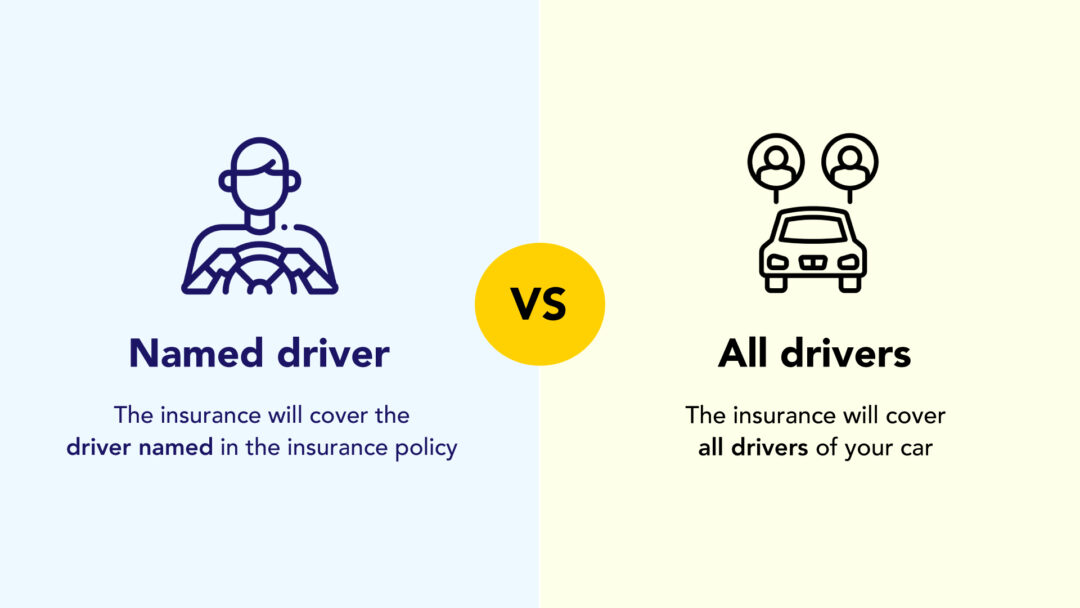
- Named Driver: Specific people (such as your spouse or child) are explicitly listed in your insurance policy. When they drive your car, they are fully covered according to your policy terms.
- All Drivers: You do not have to list every authorised driver individually. The coverage is automatically extended to any authorised driver who meets the policy conditions.
Depending on the insurer, All Drivers Coverage may be included as a default part of their product or offered as an add-on (often listed as “Waiver of Compulsory Excess for Unnamed Driver”). For instance, Generali offers an All Driver Protection option, while Berjaya Sompo’s SOMPO Motor automatically covers all authorised drivers without needing to name them.
How much does All Drivers Coverage cost?
There is no fixed price for All Drivers Coverage; it depends entirely on the insurer, the specific product, and the policy.
While older guidelines often stated that this coverage cost RM20 (with additional named drivers at RM10 each), these figures are outdated. Today:
- Free Inclusion: Providers like Syarikat Takaful Malaysia, Zurich General Takaful, Lonpac, and Takaful Ikhlas (under its Comprehensive Plus plan) currently offer All Drivers coverage for free.
- Paid Add-on: Other insurers may charge an additional premium for the waiver.
Always check your quotation and policy schedule to see whether the coverage is included automatically or if an additional premium applies.
Do you need All Drivers Coverage?
It depends entirely on how your car is used. All Drivers Coverage is highly beneficial if:
- Several family members use the same car.
- You frequently lend your car to friends or relatives.
- You want the convenience of not having to add drivers individually.
- You want to avoid the RM400 compulsory excess for an unnamed driver.
If you are the only person who ever drives your car, you likely do not need this add-on. If only one or two other people use the car, you can also consider simply adding them as Named Drivers.
What about drivers under 21 or P/L licence holders?
This is a critical detail many car owners overlook: All Drivers Coverage does not remove every type of compulsory excess.
The standard RM400 compulsory excess will still apply if the driver:
- Is below 21 years old; or
- Holds a P or L driving licence.
Even if you have All Drivers Coverage, letting your 19-year-old child drive your car does not waive this specific excess. Some insurers offer a separate waiver for young or inexperienced drivers, so check your policy carefully if this applies to your household.
How to add All Drivers Coverage
You can usually select All Drivers Coverage when buying or renewing your car insurance. If renewing online, check the available add-ons before checkout. Look for terms such as:
- All Drivers
- All Driver Cover
- Waiver of Compulsory Excess for Unnamed Driver
- Extended Driver Coverage
Make sure the exact coverage name is shown in your final quotation or policy schedule before assuming you are protected.
Easily compare car insurance add-ons
If multiple people use your car, it is worth auditing your driver coverage before your next renewal. Make sure you understand exactly who can drive, whether they need to be named, and when the RM400 excess applies.
Bjak is one of Malaysia’s leading insurance comparison platforms, allowing users to easily compare car insurance and takaful options from multiple providers to find the exact coverage they need.
Start by getting your free car insurance quote online at BJAK.