How to Check Your NCD (No Claim Discount) Before Renew Insurance
 Nabil Farhan· · 2 min read
Table of contents
Introduction
NCD, or No Claim Discount, is the discount you can get when you do not make certain insurance claims during your policy period.
Before renewing your car insurance, it is a good idea to check your NCD first. This helps you make sure the correct discount is applied and avoid paying more than necessary.
You can check your NCD online or contact your insurance company for confirmation.
What Is NCD?
NCD is a discount given to eligible private car owners based on the number of claim-free years.
The current NCD scale for private cars is:
| Claim-free period | NCD |
|---|---|
| 0 years | 0% |
| 1 year | 25% |
| 2 years | 30% |
| 3 years | 38.33% |
| 4 years | 45% |
| 5 years and above | 55% |
The maximum NCD for a private car is 55%. This means eligible policyholders can receive up to a 55% discount on the applicable base motor insurance premium.
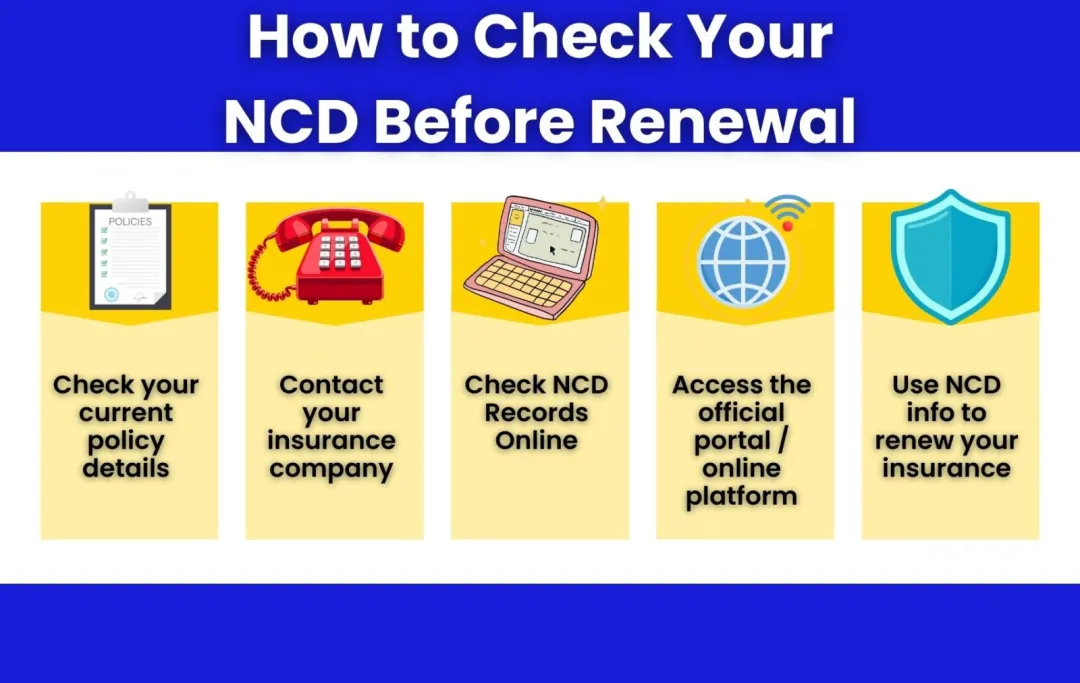
How to Check Your NCD
| Method | How to check |
|---|---|
| Contact Your Insurer | Call or email your insurance company and ask them to confirm your current NCD. |
| Online Platforms | Use an online platform that provides NCD information during the insurance renewal process. |
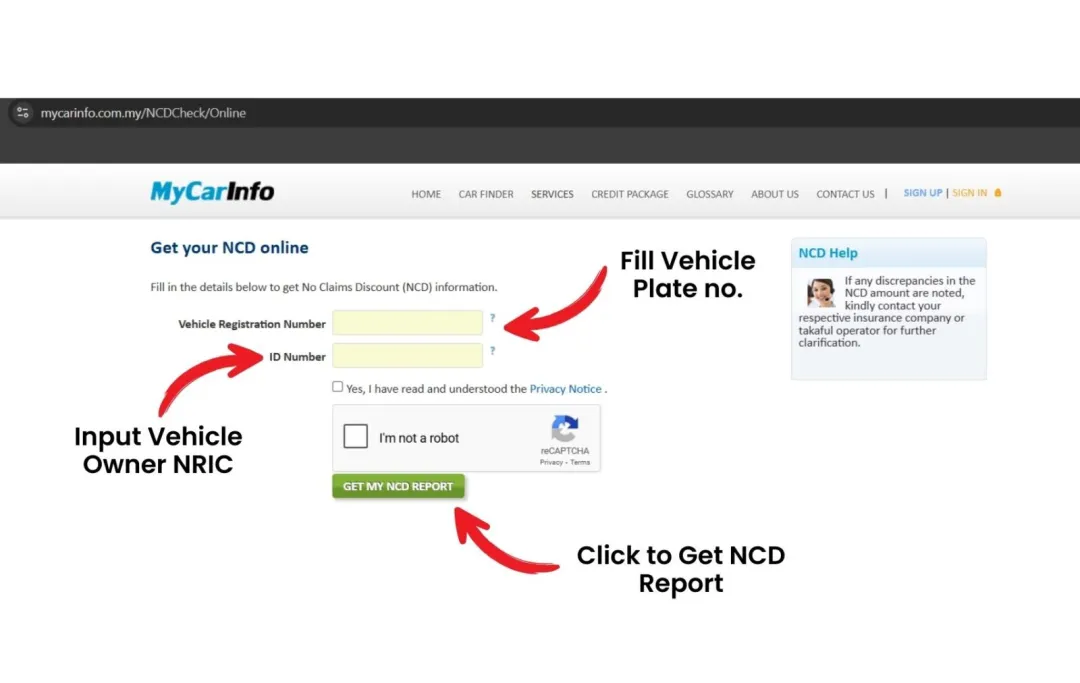
| MyCarInfo (MCI) | Visit MCI NCD Check and enter the required vehicle and owner details. |
| Previous Policy Documents | Check your previous insurance policy documents for your NCD information. |
| Insurance Agent | If you use an agent, ask them to check and confirm your NCD. |
You can also check your NCD through BJAK before getting a car insurance quotation.
Tips to Check Your NCD Properly
1. Check your NCD before renewing
Find out your current NCD before getting a new quotation. For example, if you have reached 55%, make sure the correct rate is reflected in your quotation.
2. Keep your previous policy documents
Your old policy can be useful when checking your NCD and other insurance details.
3. Check early
Do not wait until the last day to check your NCD. Checking early gives you time to clarify any differences with your insurer.
4. Compare insurance quotations
Once you know your NCD, compare insurance quotations based on the coverage you need.
Motor insurance premiums can differ between insurers because pricing takes into account factors such as the vehicle, coverage and individual risk profile.
Conclusion
Checking your NCD before renewing your car insurance can help you make sure the correct discount is applied.
For private cars, NCD starts at 25% after the first claim-free year and increases up to 55% after five years and beyond.
Before renewing, check your NCD, review your previous policy and compare quotations based on the coverage you need.
Frequently asked questions
Can I transfer my NCD to another insurer?
Yes, NCD can generally be transferred when you move to another insurer, subject to the applicable terms and conditions.
If you are transferring your NCD to a new car, the vehicle must generally be registered under the same policyholder’s name.
Will making a claim reduce my NCD?
It depends on the type of claim.
For example, an Own Damage (OD) claim where you are at fault can cause you to lose your NCD entitlement at the next renewal. Certain Own Damage Knock-for-Knock (OD-KFK) claims may not affect your NCD when the required conditions are met.
If you have reached the maximum 55% NCD, a claim that causes you to lose your NCD can have a noticeable effect on your next insurance renewal.
Can my NCD go above 55%?
No. 55% is the maximum NCD for private cars.
What if I am not sure about my NCD?
Do not guess. Check your previous policy documents, use an available online NCD checker, or contact your insurance company or agent for confirmation.