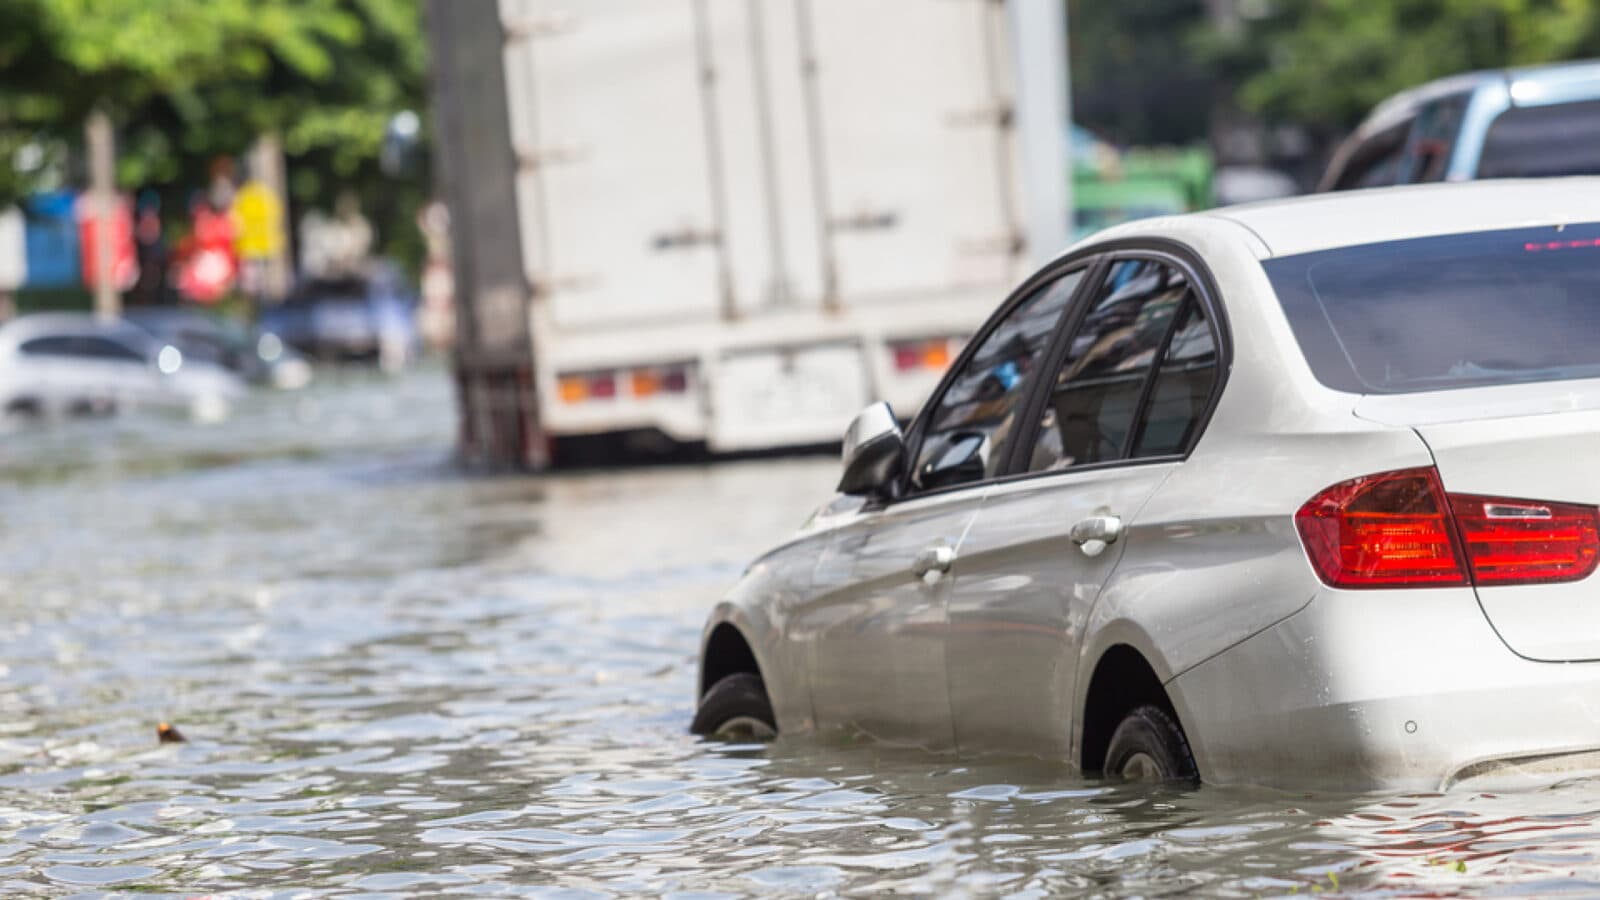
If a flood, storm or landslide damages your car, your usual comprehensive car insurance may not pay for it. Many policies list natural disasters as an exclusion unless you add a cover called special perils.
This guide explains what special perils cover includes, who needs it, what it can cost and how to add it when you buy or renew your policy.
What is special perils cover?
Special perils is an optional add-on that covers damage to your car from natural events named in your policy. On a policy schedule, you may see it written as “Inclusion of Special Perils”.
The events covered depend on the insurer or takaful operator. They commonly include:
Flood and flash flood
Storm or typhoon
Landslide
Land subsidence (sinkholes)
Earthquake
Other natural events listed in the policy wording
Insurers also differ on cases such as a tree falling on your car during a storm. Always read the wording before you rely on the cover.
Does it cover man-made accidents?
No. Special perils is for natural events. If a bus knocks down a tree and the tree lands on your car, that is usually treated as an accident, not a natural disaster. Your normal comprehensive cover would handle it instead.
Do you need special perils cover?
Malaysia rarely has earthquakes or typhoons, but floods are common, especially during the monsoon season. Your own risk depends on where you live, work and park. Consider the cover if:
Your home or workplace is in a flood-prone area
You often drive during the rainy or monsoon season
You park in low-lying areas or basement car parks
Your area has a history of landslides or strong storms
If none of these apply, you may decide the extra premium is not worth it. It is a personal decision based on risk and budget.
How much does special perils cover cost?
There is no single price. Insurers usually charge a percentage of your car’s sum insured, and the rate depends on the company and the type of cover. Here is an example from RHB Insurance, which publishes its rates for a car with a RM50,000 sum insured:
Option
Cover amount
Rate
Premium a year
Full special perils
Up to 100% of sum insured (RM50,000)
0.25%
RM125
Limited special perils
25% of sum insured, up to a maximum of 50% (RM12,500 in this example)
0.40%
RM50
These premiums are before tax and are examples only. The price you pay depends on your insurer, your sum insured and the cover you choose. You can read the details on RHB Insurance’s motor add-on page.
Other insurers price it differently. For example, our guide to special perils car insurance notes that Zurich lists its Inclusion of Special Perils at 0.2% of the sum insured a year, before service tax and stamp duty.
Is the old 0.5% rate still used?
Older articles often quote 0.5% of the sum insured as the standard rate. Do not treat that as a fixed figure today. Rates differ by company and by type of cover, so the only reliable number is the one on your current quote.
Full cover or limited cover?
Some insurers offer both options. Full cover protects up to the full value of your car. Limited cover has a lower cover amount and may carry a higher rate, so check how the figures work before you choose.
With limited cover, the insurer pays only up to the limited amount, so you pay the rest of a large repair bill yourself. Compare the premium saving against the risk of paying the difference.
What if your car is damaged by a flood?
If your car has been in floodwater, do not start the engine. Water inside the engine can cause far worse damage when it runs. Take clear photos of the car and the water level, then contact your insurer or takaful operator as soon as possible.
A claim is still subject to your policy terms, limits, excess and exclusions. Special perils helps only if the cause of damage is listed in your policy and the cover was active when the event happened.
How to add special perils cover
You can add special perils when you buy a new policy or renew an existing one. If you renew online, the add-on is usually shown before payment. Before you choose, check:
Which natural events the cover includes
The amount covered (sum insured)
Whether it is full or limited cover
The extra premium
The excess and policy exclusions
Whether a claim may affect your NCD
Do not rely on a plan name alone. Make sure special perils appears in your quotation or policy schedule.
Special perils is one of the add-ons you can compare when you get a car insurance quote on BJAK. If you live or drive in a risky area, check whether it suits your policy.
Add-ons raise your premium, so choose the ones that match your needs and budget. Compare car insurance quotes on BJAK to see what is available for your car.
Special perils is an optional add-on that covers car damage from natural events such as floods, storms and landslides. The exact events depend on your insurer and policy wording.
Does comprehensive car insurance cover floods?
Not always. Many comprehensive policies exclude natural disasters unless you add special perils. Check your policy schedule for “Inclusion of Special Perils” or ask your insurer.
How much does special perils cover cost in Malaysia?
It is usually a percentage of your sum insured, and the rate varies by company. For example, RHB Insurance lists 0.25% for full cover, which is RM125 a year on a RM50,000 sum insured, before tax.
Is a tree falling on my car covered?
It depends. A tree felled by a storm may be covered under special perils with some insurers, but a tree knocked over by another vehicle is normally an accident claim. Check your policy terms.
Can I add special perils in the middle of my policy?
It is usually added when you buy or renew your policy. Ask your insurer or agent whether mid-term changes are allowed for your policy.
Will a special perils claim affect my NCD?
Policies differ, so check your terms and ask your insurer before you claim. Do not assume the outcome.
 Nabil Farhan· · 4 min read